Skip to interview
RockStarCV.com
Toggle Navigation

Controller Mock Interview: The Strong Candidate

Hear a complete Controller interview in which Omar Haddad makes judgment, boundaries, and results inspectable.
Strong candidate pathInteractive simulation16 chapters
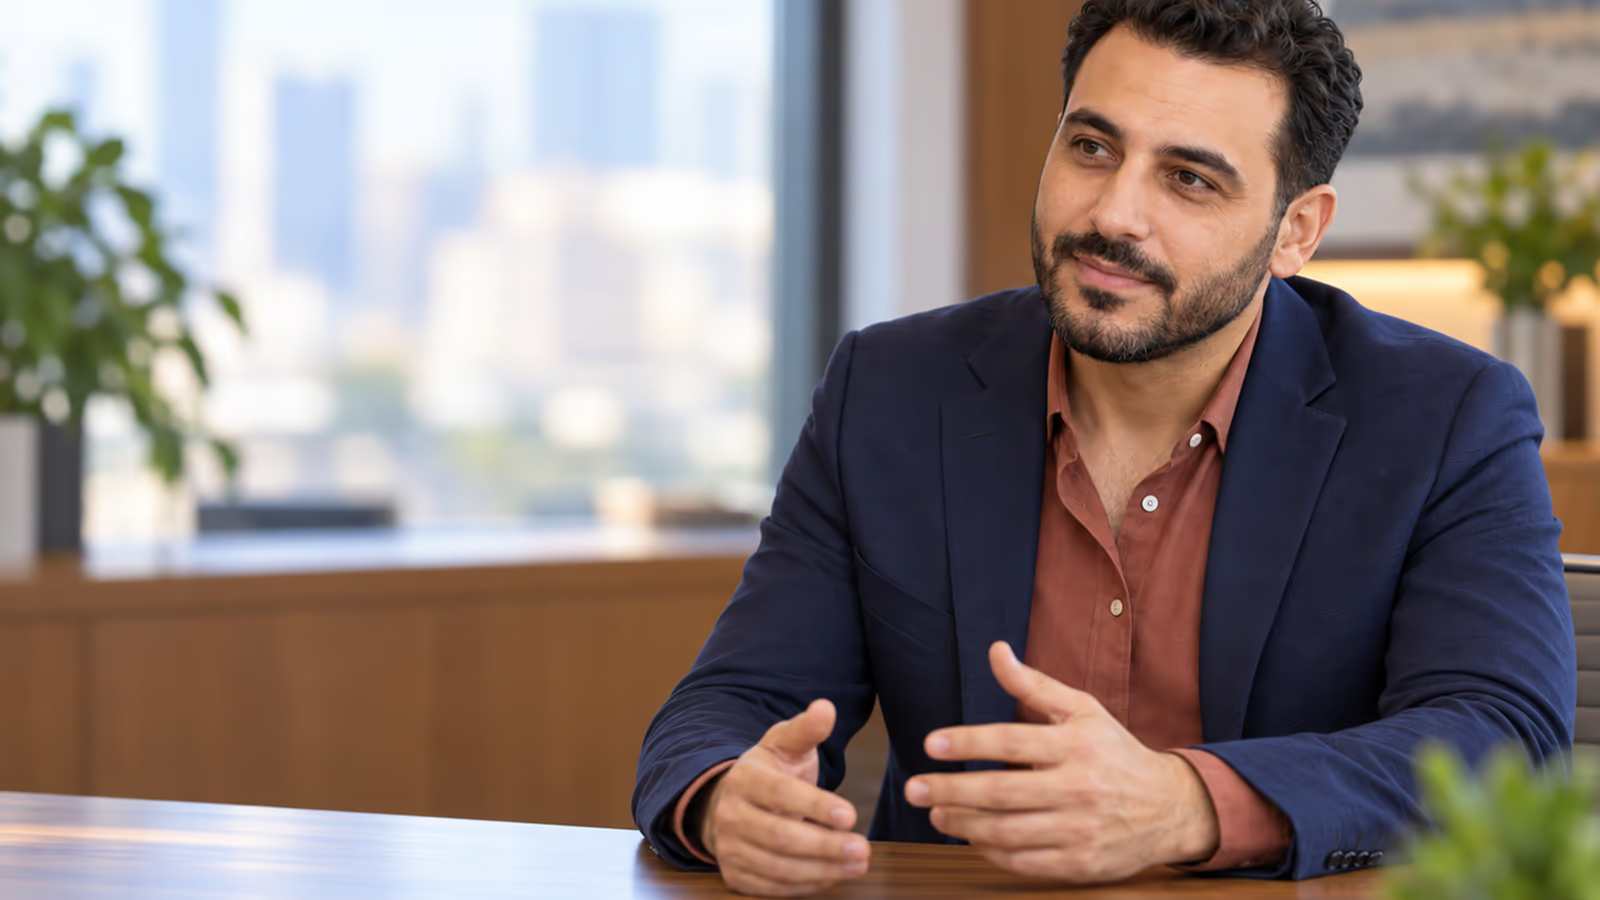
Omar Haddad, fictional Controller candidate, seated on the right and facing toward the article center
Omar HaddadController candidate

Watch and practise

Run the complete interview

Complete transcript

RockStarCV NarratorIntroduction

What does a Controller interview sound like? Let us step inside the conversation and listen for the decisions that make each answer credible.

RockStarCV NarratorMeet Priya Shah and Omar Haddad

Your interviewer is Priya Shah, Chief Financial Officer. Your candidate is Omar Haddad, presenting the strong-candidate path. After the conversation, we will turn the evidence into a practical preparation framework.

Priya ShahWelcome

Hi, Omar. Thank you for making the time. How is your day going?

Omar HaddadWelcome

It is going well, thank you. I appreciate the chance to speak with you.

Priya ShahWelcome

We will spend about half an hour on your background and several controller scenarios, then leave time for your questions. Does that work for you?

Omar HaddadWelcome

Yes, that sounds good.

Priya ShahCareer story

Walk me through your experience as a Controller.

Omar HaddadCareer story

I have built my experience around financial close, accounting policy, internal controls, reporting, audit coordination, systems, and accounting-team leadership. My recent work has required both dependable execution and clear judgment when the normal path no longer fit.

Priya ShahCareer story

What scope did you personally own?

Omar HaddadCareer story

I personally owned the record, decision path, and follow-through inside my role. I used the general ledger, reconciliations, accounting memos, control evidence, and close calendars so another person could inspect what I knew, what I decided, and where I escalated.

Priya ShahCareer story

Which result best represents your approach?

Omar HaddadCareer story

The result I value most is a more reliable operating loop: fewer ownerless handoffs, earlier risk visibility, and evidence that the intended outcome was actually reached.

Priya ShahMotivation

Why are you interested in this Controller role?

Omar HaddadMotivation

I am interested because I want to produce reliable financial reporting through controlled judgments and transparent exceptions. The role combines practical execution with judgment, and that is the responsibility I have been building toward.

Priya ShahMotivation

What about this operating environment matters to you?

Omar HaddadMotivation

I am especially drawn to an environment where hold unsupported completion and assign the accountable investigation. That makes the quality of the decision as important as the amount of activity.

Priya ShahMotivation

What would you learn first?

Omar HaddadMotivation

I would first learn the approved decision rights, the systems of record, the most consequential failure modes, and how this team verifies success before I suggest changes.

Priya ShahReconciliation close

Tell me about a time you had to address a material reconciliation break.

Omar HaddadReconciliation close

In a fictional US employer example, I had to address a material reconciliation break while the team was under normal operating pressure. I first clarified the affected people, the consequence of delay, and the decision that actually belonged to my role.

Priya ShahReconciliation close

What decision did you personally make, and what evidence did you use?

Omar HaddadReconciliation close

I used the general ledger to verify the condition, documented the trade-off, and made the next owner explicit. I also hold unsupported completion and assign the accountable investigation, so the work moved without creating a promise or decision outside my authority.

Priya ShahReconciliation close

How did you respect your authority boundary and verify the outcome?

Omar HaddadReconciliation close

I closed the loop by confirming that the balance and correction were independently reviewed. The useful evidence was the completed handoff and reviewed operating result, not simply that the team had been busy.

Priya ShahAccounting judgment

Tell me about a time you had to evaluate a nonstandard transaction.

Omar HaddadAccounting judgment

In a fictional US employer example, I had to evaluate a nonstandard transaction while the team was under normal operating pressure. I first clarified the affected people, the consequence of delay, and the decision that actually belonged to my role.

Priya ShahAccounting judgment

What decision did you personally make, and what evidence did you use?

Omar HaddadAccounting judgment

I used reconciliations to verify the condition, documented the trade-off, and made the next owner explicit. I also document facts policy alternatives and approval, so the work moved without creating a promise or decision outside my authority.

Priya ShahAccounting judgment

How did you respect your authority boundary and verify the outcome?

Omar HaddadAccounting judgment

I closed the loop by confirming that the recorded treatment was traceable to reviewed guidance. The useful evidence was the completed handoff and reviewed operating result, not simply that the team had been busy.

Priya ShahControl deficiency

Tell me about a time you had to respond to a repeated control failure.

Omar HaddadControl deficiency

In a fictional US employer example, I had to respond to a repeated control failure while the team was under normal operating pressure. I first clarified the affected people, the consequence of delay, and the decision that actually belonged to my role.

Priya ShahControl deficiency

What decision did you personally make, and what evidence did you use?

Omar HaddadControl deficiency

I used accounting memos to verify the condition, documented the trade-off, and made the next owner explicit. I also contain current risk and address design or execution cause, so the work moved without creating a promise or decision outside my authority.

Priya ShahControl deficiency

How did you respect your authority boundary and verify the outcome?

Omar HaddadControl deficiency

I closed the loop by confirming that remediation was tested across a defined period. The useful evidence was the completed handoff and reviewed operating result, not simply that the team had been busy.

Priya ShahAudit

Tell me about a time you had to handle an auditor request revealing weak evidence.

Omar HaddadAudit

In a fictional US employer example, I had to handle an auditor request revealing weak evidence while the team was under normal operating pressure. I first clarified the affected people, the consequence of delay, and the decision that actually belonged to my role.

Priya ShahAudit

What decision did you personally make, and what evidence did you use?

Omar HaddadAudit

I used control evidence to verify the condition, documented the trade-off, and made the next owner explicit. I also provide facts without manufacturing support after the event, so the work moved without creating a promise or decision outside my authority.

Priya ShahAudit

How did you respect your authority boundary and verify the outcome?

Omar HaddadAudit

I closed the loop by confirming that the gap and corrective action remained transparent. The useful evidence was the completed handoff and reviewed operating result, not simply that the team had been busy.

Priya ShahTeam leadership

Tell me about a time you had to reduce close burnout without weakening control.

Omar HaddadTeam leadership

In a fictional US employer example, I had to reduce close burnout without weakening control while the team was under normal operating pressure. I first clarified the affected people, the consequence of delay, and the decision that actually belonged to my role.

Priya ShahTeam leadership

What decision did you personally make, and what evidence did you use?

Omar HaddadTeam leadership

I used close calendars to verify the condition, documented the trade-off, and made the next owner explicit. I also redesign sequence ownership and automation using risk, so the work moved without creating a promise or decision outside my authority.
Priya ShahTeam leadership

How did you respect your authority boundary and verify the outcome?

Omar HaddadTeam leadership

I closed the loop by confirming that close effort fell while review quality held. The useful evidence was the completed handoff and reviewed operating result, not simply that the team had been busy.

Priya ShahCandidate questions

What questions would you like to ask us?

Omar HaddadCandidate questions

What would make someone in this role demonstrably successful after six months?

Priya ShahCandidate questions

Success means reliable judgment, clear ownership, and evidence that the work improves the customer or patient outcome. We would agree the exact measures during onboarding.

Omar HaddadCandidate questions

Which decisions would I own, and which should I escalate?

Priya ShahCandidate questions

You would own routine decisions inside the role and use documented escalation paths when risk, scope, or authority changes. We value early escalation with a clear recommendation.

Omar HaddadCandidate questions

Thank you. That is helpful.

Priya ShahClose

Those are all my questions. Thank you, Omar. We will follow up after the remaining interviews.

Omar HaddadClose

Thank you for the conversation. I appreciate your time.

RockStarCV NarratorOutro 1 · Verdict

Omar Haddad made judgment visible instead of asking the interviewer to infer it. The answers connected a constraint, a personal decision, and a verifiable result.

RockStarCV NarratorOutro 2 · Evidence

Strong does not mean perfect. It means the interviewer can inspect how the candidate thought and what changed.

RockStarCV NarratorOutro 2 · Evidence

The recurring evidence was address a material reconciliation break, evaluate a nonstandard transaction, contain current risk and address design or execution cause, and the gap and corrective action remained transparent.

RockStarCV NarratorOutro 2 · Evidence

Notice that the examples are fictional composites. The teaching principles come from the cited occupation and practice sources, not from invented outcomes.

RockStarCV NarratorOutro 3 · Framework

Prepare your own answer with five lines: context, evidence, decision, boundary, verification.

RockStarCV NarratorOutro 3 · Framework

Keep each line short enough to say naturally, then let the interviewer decide where to probe.

RockStarCV NarratorOutro 4 · Practice

Pause here and rehearse one real controller example. Replace team language with the decision you personally owned, and do not claim an outcome you cannot verify.

RockStarCV NarratorOutro 4 · Practice

Prepare with evidence. Interview with confidence.

Use Play to hear the conversation, move one slide at a time, or jump directly to a chapter. Captions follow the active speaker.

What to expect

How the interview is likely to unfold

A senior controller interview usually moves from your career story into evidence of judgment, then closes with your questions.

  1. Career story

    Walk me through your experience as a Controller.

  2. Motivation

    Why are you interested in this Controller role?

  3. Reconciliation close

    Tell me about a time you had to address a material reconciliation break.

  4. Accounting judgment

    Tell me about a time you had to evaluate a nonstandard transaction.

  5. Control deficiency

    Tell me about a time you had to respond to a repeated control failure.

  6. Audit

    Tell me about a time you had to handle an auditor request revealing weak evidence.

  7. Team leadership

    Tell me about a time you had to reduce close burnout without weakening control.

Who might interview you

Different people are testing different things

Listen to the role behind the question. The same example may need a different emphasis for each interviewer.

Chief Financial Officer

Their purpose
Evaluate role judgment, ownership, boundaries, and evidence.
They look for
address a material reconciliation break, evaluate a nonstandard transaction, contain current risk and address design or execution cause

Cross-functional partner

Their purpose
Understand collaboration and escalation.
They look for
A clear decision path and honest operating boundary.

Senior peer

Their purpose
Test realistic execution detail.
They look for
Specific examples and verification.

What they are assessing

Make your judgment easy to see

What interviewers need to learn

  • Do you make address a material reconciliation break visible?
  • Do you make evaluate a nonstandard transaction visible?
  • Do you make contain current risk and address design or execution cause visible?
  • Do you make the gap and corrective action remained transparent visible?
  • Do you make reduce close burnout without weakening control visible?

Accentuate

  • Context: Define the affected people, system, and consequence in Controller work.
  • Evidence: Use the general ledger, reconciliations, accounting memos, control evidence, and close calendars to verify the condition before acting.
  • Decision: Name the decision you personally owned and the trade-off you accepted.
  • Boundary: State what required approval, licensed judgment, or accountable escalation.
  • Verification: Close with the reviewed result, denominator, or completed handoff.

Leave out

  • Unbounded team language with no personal decision.
  • Activity presented as an outcome.
  • A promise outside your authority.
  • A number you cannot verify.

Difficult questions

Prepare the evidence, not a script

Use these prompts to choose a truthful example and reconstruct the decision. Your delivery should still sound like you.

Tell me about a time you had to address a material reconciliation break.

Why they ask: They are testing reconciliation close judgment.

Prepare: I used the general ledger to verify the condition, documented the trade-off, and made the next owner explicit. I also hold unsupported completion and assign the accountable investigation, so the work moved without creating a promise or decision outside my authority.

Tell me about a time you had to evaluate a nonstandard transaction.

Why they ask: They are testing accounting judgment judgment.

Prepare: I used reconciliations to verify the condition, documented the trade-off, and made the next owner explicit. I also document facts policy alternatives and approval, so the work moved without creating a promise or decision outside my authority.

Tell me about a time you had to respond to a repeated control failure.

Why they ask: They are testing control deficiency judgment.

Prepare: I used accounting memos to verify the condition, documented the trade-off, and made the next owner explicit. I also contain current risk and address design or execution cause, so the work moved without creating a promise or decision outside my authority.

Tell me about a time you had to handle an auditor request revealing weak evidence.

Why they ask: They are testing audit judgment.

Prepare: I used control evidence to verify the condition, documented the trade-off, and made the next owner explicit. I also provide facts without manufacturing support after the event, so the work moved without creating a promise or decision outside my authority.

Tell me about a time you had to reduce close burnout without weakening control.

Why they ask: They are testing team leadership judgment.

Prepare: I used close calendars to verify the condition, documented the trade-off, and made the next owner explicit. I also redesign sequence ownership and automation using risk, so the work moved without creating a promise or decision outside my authority.

100 interview questions

Controller Interview Questions: 100 Answers

Keep preparing with the complete question book created for Controller interviews.

View the question book
Front-facing 3D book mockup of Controller 100 Job Interview Questions, an interview question book from RockStarCV.com.

How to use this simulation

Listen for decisions, not polished phrases

Pause after each question and form your own answer before Omar Haddad responds. Then compare the evidence provided: the constraint, the decision, the personal contribution, the trade-off, and the result.

Priya Shah and Omar Haddad are fictional composite characters. Their employers, controller examples, figures, and outcomes were created for teaching purposes.

Take the interview with you

Your controller interview playbook

Use the printable framework to prepare examples, test your evidence, and rehearse stronger answers away from the screen.

  • Question prompts
  • Evidence checklist
  • Practice notes
Download the PDF playbook

What to notice

A practical viewing checklist

  1. 01

    Listen for address a material reconciliation break.

  2. 02

    Listen for evaluate a nonstandard transaction.

  3. 03

    Listen for contain current risk and address design or execution cause.

  4. 04

    Listen for the gap and corrective action remained transparent.

  5. 05

    Listen for reduce close burnout without weakening control.

Interviewer scorecard

The signals behind a credible answer

Research foundation

Sources behind the teaching principles

The sources support the interview guidance, not the fictional candidate’s invented employers, budgets, dates, or outcomes.

Similar interviews

Explore related mock interviews

More from RockStarCV

Build your complete career toolkit